UK e-invoicing roadmap: What businesses need to know
What HMRC’s new roadmap means for Peppol, EDI and UK e-invoicing readiness ahead of the April 2029 mandate.
November 2026: The roadmap is out, and Peppol is at the center of it
In our April update, we said Budget 2026 was the one to watch. It delivered. On October 28, alongside the Autumn Budget, HMRC published its e-invoicing implementation roadmap. For the first time, we know how the UK model will work, not just when it starts.
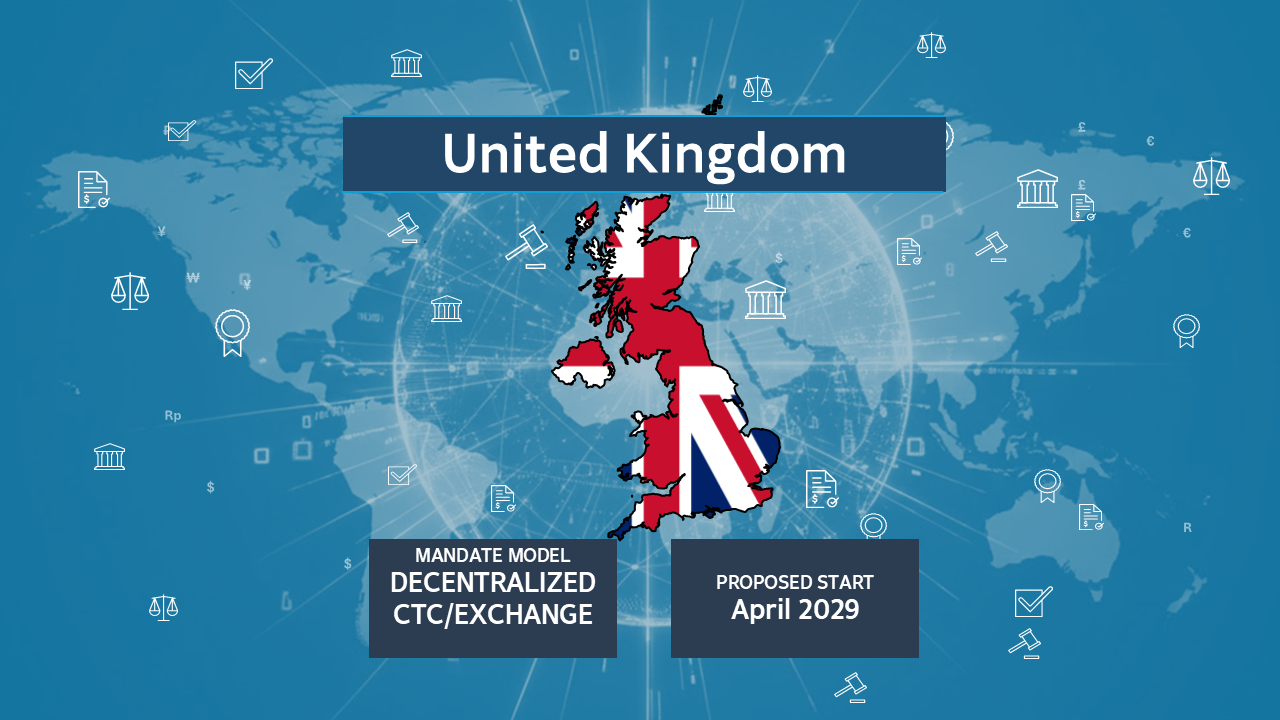
The date holds: From April 1, 2029, VAT-registered businesses, including public sector bodies, must issue and receive VAT invoices as structured e-invoices. The model is the one we’ve been expecting since August 2025: decentralized, built on Peppol, with no invoice clearance by HMRC.
UK e-invoicing at a glance
- Effective date: April 1, 2029
- Scope: Domestic B2B and B2G VAT invoices
- Framework: Peppol
- EDI: Existing EDI arrangements can continue, but businesses will also need to support the Peppol-based framework
- Invoice reporting to HMRC: Not part of the 2029 model, although HMRC is consulting separately on potential future digital reporting.
What does the UK e-invoicing roadmap confirm?
Scope: Domestic B2B and B2G. The requirement applies to taxable supplies between VAT-registered persons in the UK where a VAT invoice is needed. Public bodies registered for VAT are in. Non-established businesses registered for UK VAT are treated the same as UK businesses. B2C, cross-border, exempt and zero-rated supplies are out, although anyone can use e-invoicing voluntarily. There is no phasing by size: everyone in scope starts on the same day.
A PDF is not an e-invoice. The roadmap is explicit: PDFs, Word files, images and HTML invoices won’t count. An e-invoice is structured data that software can read without human help.
Peppol is the backbone. The UK will use Peppol as its interoperability framework, in a four-corner model. Suppliers and buyers exchange invoices through certified Peppol Access Points, usually via their software or e-invoicing provider. HMRC is not in the invoice flow and doesn’t validate invoices before they reach the buyer.
HMRC becomes the UK Peppol Authority. Today that role sits with NHS Supply Chain. HMRC will take it over, but the roadmap doesn’t give a date yet. Access Points will need OpenPeppol certification, possibly with UK-specific requirements on top, and accreditation with the UK Peppol Authority by April 2029.
Businesses must be findable. Every business will need a Peppol participant identity so its trading partners can route invoices to it. Which business identifiers the UK will accept is still open and will be decided between October 2027 and April 2028.
No invoice reporting to HMRC, for now. The Peppol Authority won’t receive copies of business invoices. But HMRC has opened a separate consultation on e-invoicing digital reporting, asking whether selected invoice data could be shared with HMRC later. It closes on January 20, 2027. No decision has been taken, so “no reporting” describes 2029, not necessarily the years after.
Can businesses keep using EDI alongside Peppol?
This is the point many of our UK customers have been waiting for. Plenty of them have invoiced electronically for decades over EDI, and back in February 2025 we argued that forcing them to rip that out would make no sense. The roadmap agrees. The government’s stated intention is that businesses can keep their existing EDI arrangements alongside the new framework.
But read the second half of that sentence too. Businesses using EDI will also need to be able to exchange e-invoices through the Peppol-based framework. In practice, that means a company may run both: EDI with the trading partners who already use it, and Peppol with everyone else, all from the same ERP and accounts payable and receivable processes.
That’s an integration question as much as a compliance one. Which trading partners should remain on EDI? How do Peppol and EDI invoices land in the same accounts payable (AP) workflow? How do you keep one view of invoice status across both? HMRC has promised further EDI guidance in autumn 2027, but companies with large, complex B2B communities shouldn’t wait for it to start mapping their partners.
What happens next?
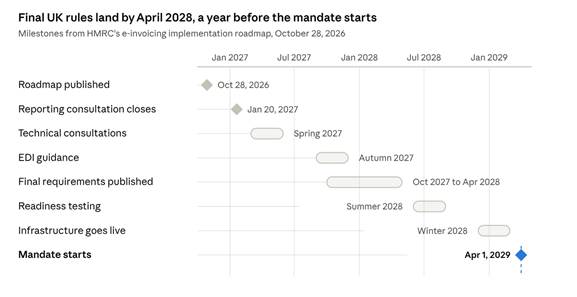
Primary legislation is expected through Finance Bill 2026 in spring 2027, with the secondary legislation possibly not finished until autumn 2028 or early 2029. HMRC says it won’t change the requirements after April 2028 unless stakeholder feedback makes it necessary, so from then on, businesses have a fixed target.
What should businesses be doing now?
The final technical rules won’t be published until October 2027 to April 2028. That doesn’t mean there’s nothing to do:
- Map your invoice flows. List every system that issues or receives VAT invoices in the UK, inbound and outbound, direct and indirect. That inventory is the starting point for everything else.
- Map your trading partners by channel. Who’s on EDI, who’s on Peppol already (NHS suppliers often are), and who still gets PDFs or paper. The paper and PDF group is your 2029 problem.
- Respond to the consultations. The digital reporting consultation closes on January 20, 2027, and the technical consultations follow in spring 2027. This is the window to shape the rules.
- Look beyond the UK. For multinationals, the UK joins a long list: Belgium and Poland went live this year, France in September, Germany’s next phase starts in January 2027, and Spain in October 2027. Solving each country with a different provider gets expensive fast.
How OpenText can help
The UK roadmap plays to two things OpenText already does: Peppol and B2B integration. OpenText™ Trading Grid™ connects ERP, finance and procurement systems to trading partners over EDI, Peppol and other channels from one platform. That matters for exactly the coexistence the roadmap describes: keep your EDI relationships, add Peppol where you need it, and run both as one managed process.
OpenText is a certified Peppol Access Point, and we plan to seek accreditation with the UK Peppol Authority ahead of April 2029. Trading Grid supports EDI and Peppol side by side for the same customer, so you don’t have to choose one channel or run two separate projects.
Preparing for UK e-invoicing? Contact OpenText to discuss your UK readiness, including how to support EDI and Peppol alongside European mandates already live or coming. We’ll cover the technical consultation and final requirements as soon as they land.
Contact an OpenText e-Invoicing expert.
Sources
- HMRC: Roadmap for e-invoicing implementation, October 28, 2026
- HMRC: E-invoicing digital reporting consultation, closes January 20, 2027
- KPMG: UK publishes B2B e-invoicing roadmap from April 2029
- Deloitte: Budget 2026, electronic invoicing implementation roadmap
- VATupdate: UK publishes B2B e-invoicing roadmap
April 2026
The cogs are turning: Budget 2026 is the one to watch
Since our November update, the wheels have been turning quietly behind the scenes at HMRC – which is exactly what we’d expect at this stage of the process.
As promised, HMRC launched its stakeholder collaboration phase in January 2026, bringing together software providers, tax advisors, and businesses of all sizes to co-design the final regime. No dramatic announcements yet – this is the unglamorous but essential groundwork phase where the real decisions get made.
The next major milestone? Budget 2026, where the government has committed to publishing the full implementation roadmap and technical standards. That’s when the “how” finally gets answered – formats, interoperability requirements, platform certification, and the timeline detail that businesses and their software vendors have been waiting for.
A couple of things worth noting in the meantime:
The Peppol signal is getting stronger.
The January collaboration process has reinforced what we suspected back in August 2025 – the UK’s decentralised model is converging on Peppol/EN 16931 as its interoperability backbone, keeping the UK digitally compatible with its largest trading partners in Europe despite Brexit removing the UK from any legal need to comply with ViDA.
Real-time reporting is off the table – for now.
This was confirmed in the Budget 2025 consultation response but bears repeating: the 2029 mandate will not require businesses to feed live transaction data to HMRC. If you’ve been worried about giving the taxman a window into every invoice as it flies out the door, you can breathe easy — at least for the initial rollout.
What should you be doing right now?
Honestly, there’s not much businesses can be doing, since little has changed – so our advice remains the same.
2029 is still a while off; but please pay attention to the upcoming budget. The technical standards arriving at Budget 2026 will make it feel considerably less distant. If you haven’t already had a conversation with your OpenText account representative about your readiness, now is a good time – particularly if you’re a multinational managing the UK alongside a raft of European mandates that are already live or imminent.
The starting gun was fired in November. Budget 2026 is when the course gets marked out.
November 2025
It’s official! The UK mandates e-Invoicing for 2029 – and you heard it here first!
Well, ladies and gentlemen, the waiting game is officially over.
After months of patiently observing HMRC’s quiet review of their e-invoicing consultation, and following their vague-but-committed “Transformation Roadmap”, the government has delivered the definitive answer: mandatory e-invoicing is coming in 2029!
As I pointed out in our August blog, the Transformation Roadmap language sounded decidedly decentralized and for my money was leaning towards a PEPPOL-based interoperability model, so it’s deeply satisfying to see the official response align perfectly with my predictions (and frankly, with common sense).
The Mandate Breakdown: Predictable, yet challenging
HMRC’s decision to introduce mandatory e-invoicing for all VAT invoices from 2029 is a game-changer. This isn’t just about a nudge towards digital; it’s a commitment to joining the global CTC (Continuous Transaction Controls) movement that’s already sweeping Europe.
But here’s where the “I told you so” moment gets interesting (in the nicest possible way, of course):
- The Model is Decentralized: The government explicitly favors a decentralized model, aligning perfectly with the inference we drew from the Transformation Roadmap last August, which suggested HMRC would rely on intermediaries/software providers instead of building a massive, monolithic government portal. This also aligns perfectly with our previous analysis that a decentralized model is the best model to serve the needs of UK businesses.
- The PEPPOL Hunch: Our earlier suggestion that we shouldn’t “bet against a PEPPOL based model” looks increasingly solid. The decentralized model is compatible with the existing MTD framework and strongly suggests leveraging the proven standards used successfully by the NHS for e-procurement.
Why the Rush? It’s all about the cash!
For a country that has been happy to “sit back and observe” e-invoicing in others, this 2029 deadline may feel fast. But the drivers are impossible to ignore:
- The VAT Gap: While MTD addressed the VAT return, e-invoicing tackles the transaction level, helping to close the VAT gap (estimated at £8.1bn in the 2022-2023 tax year).
- The Late Payments Plague: This is the big one. The mandate is intended to solve the business pain point of late payments, with research showing e-invoicing can reduce late payments by 20% and save small firms £11,300 annually. That’s real, tangible ROI.
Compliance will be an integration challenge
This decentralized, standards-based approach creates a huge network integration challenge—which is fortunately exactly where we shine.
We have long advocated that the ideal model serves both the tax agency and businesses. The decentralized model achieves this, but for large multinationals it will require an integration partner to simplify the complexity:
- 100% Community Enablement: The new mandate ensures all suppliers must comply, forcing even small and micro businesses to engage. Our platform specializes in providing scalable enablement tools to onboard every trading partner quickly and cost-effectively.
- Decentralized Mastery: We already connect to decentralized platforms across Europe (like Chorus Pro in France) and are key players in the PEPPOL network. This means we aren’t scrambling to adapt; we already live here.
- Integration is our Core: Forget the piecemeal, multi-vendor approach. We solve the core problem by integrating your ERP, finance, and procurement systems into a single data process flow, reducing processing time, cutting costs by 60-80%, and simplifying the inevitably complex UK standard.
The starting gun has officially been fired. 2029 is much closer than you think when you consider the complexity of multi-country integrations and data readiness.
Don’t let the UK become a last-minute compliance headache. Instead turn this mandate into a huge competitive advantage.
Reach out to your OpenText account representatives today to discuss the implications.
August 2025
HMRC’s Transformation Roadmap – early days, but inferences may be drawn
If you’ve been following our coverage of the UK’s e-invoicing journey, you’ll know things have hit a quiet patch. After HMRC’s 12-week consultation (see below), there has been a natural lull while they review the input.
HMRC’s Transformation Roadmap
On July 21, 2025, HMRC published a new document—their “Transformation Roadmap.” While the main body of the document doesn’t explicitly mention electronic invoicing, a closer examination reveals a clear commitment. Tucked away in Annex B, we found this key line:
“HMRC will: Explore increasing the adoption of e-invoicing as a means of reducing administrative burdens, improving cashflow, and reducing errors for VAT customers.
So the good news is, HMRC definitely has e-Invoicing in the plan, but it’s clear things remain very much in the early stages. The roadmap, then, is more of a high-level vision than a step-by-step timeline. It’s short on specifics and long on lofty goals, but their stated aim of reaching a “digital-first” tax system by 2030 gives some idea of the timelines that they are shooting for.
We can also draw a few other inferences if not conclusions from the language used. Consider this quote from the roadmap itself (emphasis mine):
“HMRC envisages that the role of intermediaries in administering the tax and customs system will increase. Intermediaries, such as software providers, are already becoming more integrated into customers’ existing processes and systems. This integration allows for AI and other technological innovations to automate fulfilment of customers’ tax and customs obligations.“
This statement seems to point towards a decentralized model, where the government relies on private software providers, like OpenText, to handle the technical heavy lifting of e-invoicing. It suggests that instead of building a massive, all-encompassing government portal, HMRC intends to leverage the existing market of service providers.
Elsewhere in previous documents HMRC has mentioned PEPPOL – no surprise given the success seen by the NHS in their national roll-out for e-procurement. If I were a betting man I would certainly not want to bet against a PEPPOL based model for the UK by 2030.
“Wait and learn”
It’s clear that the UK has been quietly sitting back and observing the implementation of e-Invoicing in other countries – the successes of the PEPPOL-based models and the stumbles of some centralized systems. But the result is that HMRC is now in a good position to design a model that works for its unique ecosystem.
However, in the short term this also means a degree of vagueness and uncertainty for businesses.
What is clear is that a “digital-first” approach is no longer merely an aspiration but an explicit goal. While the timeline is still being decided, the line in the sand drawn by the Transformation Roadmap is undeniable. 2030 is not that far away at all now, a mere five years. This means companies need to start considering the implications now. For UK Headquartered multinationals with operations across Europe now is the time to consider your overarching e-Invoicing strategy. With mandates coming soon in Belgium, Poland, France, Croatia and others it’s vital that businesses take the long term view and invest in a platform that can scale to meet the tidal wave of e-Invoicing reforms on the way.
So, let’s keep calm and carry on for now while monitoring the evolution of HMRC’s digital transformation roadmap. The UK may be a late starter in the e-invoicing race, but it looks like the starting gun has finally been fired.
You can find a full copy of HMRC’s Transformation Roadmap here, and the Annex B here.
OpenText are committed to supporting our customers and prospects through the UK’s journey. Stay tuned for more updates when we have them, and learn how to simplify mandates and unlock measurable ROI with OpenText’s e-Invoicing Solutions.
February 2025
New developments in HMRC’s e-Invoicing consultation
As you saw in my previous blog post back in September 2024, the UK government announced an open consultation on promoting electronic invoicing (e-invoicing) across businesses and the public sector. Now, there’s exciting progress to share!
Key Aspects of the Consultation
The consultation, which is a significant step towards standardizing e-invoicing in the UK, has now officially kicked off. Commencing on February 13, 2025, it will run until May 7, 2025. This consultation aims to gather a wide range of views on how best to implement e-invoicing. The goal is to enhance business productivity, improve cash flow, reduce administrative burdens, and minimize errors in tax returns.
One of the key aspects being explored is whether e-invoicing should be voluntary or mandatory. There’s also a lively discussion on the merits of centralized versus decentralized models and the potential for real-time reporting. The government is keen to hear from businesses of all sizes and sectors to ensure the approach developed is both practical and beneficial.
To facilitate this, HM Revenue & Customs (HMRC) and the Department for Business & Trade (DBT) are organizing various events to engage with businesses and gather their input. This is a fantastic opportunity for businesses to have their say and help shape the future of invoicing in the UK.
Benefits of e-invoicing
From our perspective, the benefits of a mandatory e-invoicing regime to both businesses and tax agencies are clear. For businesses, automating all inbound and outbound invoice transactions substantially reduces the overhead of labor-intensive manual processes, virtually eliminates errors, and significantly reduces late payments. This will have real cash flow benefits for businesses at a time when the economy is struggling.
For tax agencies, a mandatory e-invoicing regime delivers greater visibility into the economy and significantly reduces the time and cost associated with tax audits. Many tax agencies have seen a significant reduction in their VAT gap as a result of such mandatory e-invoicing reforms, potentially representing billions of pounds in additional revenue for the UK.
Models and approaches
However, it is vital that any mandate must put the needs of businesses first. Many of our customers here in the UK have been invoicing electronically for decades, leveraging the existing provisions in UK tax law for voluntary e-invoicing. Forcing them to change a process that has worked reliably for years is unnecessary.
While we have seen many different models implemented globally, the best model for e-invoicing that serves the needs of both the tax agency and businesses has proven to be a decentralized one. Unlike the centralized or clearance models used in Italy and proposed in Poland, a decentralized model does not force taxpayers to use a central government portal to deliver their invoices. A decentralized model allows suppliers to send e-invoices directly to their buyers. In parallel, real-time or near-real-time reports of invoice transactions can be transmitted to a government portal to provide visibility to HMRC, as has been proposed in countries such as France, Greece, Croatia, Latvia, and others. This approach minimizes disruption to businesses that have already implemented e-invoicing while giving those who have not yet done so maximum flexibility in how to send or receive e-invoices.
Participating in the consultation
For more information about the consultation process and details of how to submit your responses to HMRC, see the official documentation here.
If you’d like to discuss the different approaches laid out in the consultation in order to better respond to the consultation, please feel free to reach out to your OpenText account representatives who can arrange a discussion with our subject matter experts, or contact us here.
Stay tuned for more updates as the consultation progresses.
September 2024
Embracing the future: HMRC announce consultation on mandatory e-Invoicing
The UK government has recently announced an exciting development that could revolutionize the way businesses handle invoicing. As part of a broader package of reforms, His Majesty’s Revenue and Customs (HMRC) will soon launch a consultation on the implementation of mandatory electronic invoicing (e-Invoicing) across UK businesses and government departments.
A step towards digital transformation
This consultation marks a significant step towards a digital-first approach, aiming to streamline administrative tasks, improve cash flow, boost productivity, and reduce errors in tax returns while enhancing overall business efficiency.
From the government’s perspective, this is seen as a key initiative in improving the UK’s tax system and helping to fix the foundations of the UK economy, and close the VAT gap, which at last count (2022-2023 tax year) was estimated to be approximately £8.1bn.
What does this announcement mean?
This is exciting news for all UK businesses. While e-Invoicing has been an option for businesses for many years, its adoption has been hampered by limitations derived from the European Union VAT Directive (Council Directive 2006/112/EC). This directive included provisions that allowed buyers to refuse electronic invoices, insisting on paper instead.
HMRC VAT Notice 700/63 outlines the conditions for e-Invoicing, transposing many key conditions from the EU VAT directive, including the obligation for buyer acceptance. This has been a major barrier to widespread adoption.
However, recent e-Invoicing mandates in Europe have reversed this restriction, preventing buyers from vetoing electronic invoices and mandating that all invoices be exchanged electronically.
The benefits of mandatory e-Invoicing
The implementation of a mandate will have many benefits, not just for the UK government, but for businesses.
- Efficiency: Automating invoicing processes reduces manual errors and saves time.
- Cost Savings: Lower administrative costs and faster payment cycles.
- Environmental Impact: Reducing paper usage contributes to sustainability efforts.
- Tax compliance: Ensures adherence to the latest tax regulations and reduces the risk of compliance errors and fraud
Looking ahead
As HMRC prepares to gather input from businesses on how to best implement e-Invoicing, we encourage our customers to participate in the consultation process. Your feedback is invaluable in shaping a system that works for everyone.
As a global provider of e-Invoicing services, OpenText we have long supported the existing optional regime for B2B e-Invoicing in the UK and have been a key player in providing PEPPOL-based e-Invoicing solutions for the NHS. Our commitment to innovation and excellence means we are well-prepared to support any new mandatory regime that the UK government might propose.
We are committed to supporting our customers and prospects through this transition and beyond. Stay tuned for more updates as we navigate this exciting journey towards a more efficient and digital future.
For more details of HMRC’s announcement, see the official press release on the UK government’s website here. Learn more about OpenText e-Invoicing solutions.
Disclaimer: This blog is intended to reflect the direction the industry is moving and does not a reflect a commitment for the OpenText Trading Grid e-Invoicing (formerly Active Invoices with Compliance) product development roadmap to meet any particular stated regulations.
LEGAL Disclaimer: The information contained in this newsletter is for general guidance on matters of interest only. The authors are not herein rendering legal, accounting, tax or other professional advice and the content should not be used as a substitute for consultation with professional accounting, tax, legal or other competent advisers. While we make every attempt to ensure the accuracy of the information contained within is from reliable sources, OpenText is not responsible for any errors or omissions, or for any result.